Borrow Cash Instantly WeDollar

Screenshots
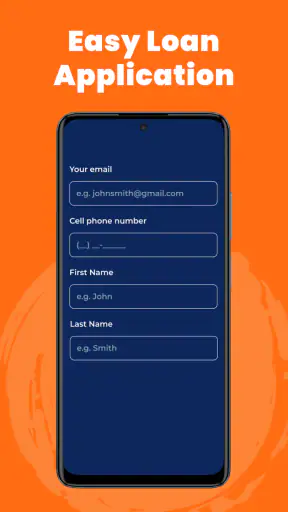
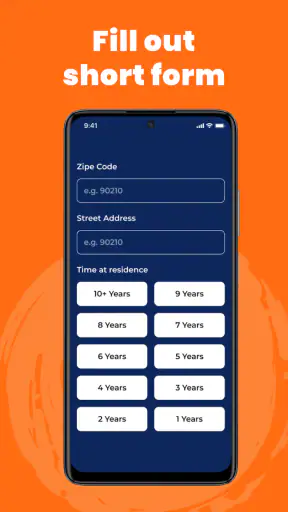
Details
- Rating
- 1.02K reviews
- Version
- 2.0.2
- Developer
- Voronkov Moner App
Analysis by Norviv
Before I open a cash-advance app, I want to know what problem I’m trying to solve, what amount would actually cover it, and how repayment would fit around bills that are already due. That matters especially with Borrow Cash Instantly WeDollar: its purpose is focused, but a quick mobile process still calls for a slow financial decision. I see it as a way to explore an advance for a specific short-term gap, not as a substitute for income or a complete banking relationship.
My overall view is cautiously positive. The app is free to install, is rated for Everyone, and has a 4.7 average from around 30 thousand ratings, with over 100 thousand installs. That gives a sense of its reach, but popularity cannot tell me whether an individual offer suits someone’s budget. I would treat every borrowing decision as personal and check the repayment details before proceeding.
Start with the decision, not the application
I would first write down the expense, its deadline, and the smallest amount that would resolve it. That simple step helps distinguish a genuine urgent need from a tempting chance to borrow more than necessary. It also gives me a fair basis for comparing an advance with other routes, instead of judging it only by how quickly the app lets me begin.
For example, imagine a necessary household item fails just before payday. If waiting would cause a real problem, I might check whether WeDollar presents an option that covers the immediate replacement. Before accepting, I would compare the amount I need with the amount offered, note the total repayment and timing shown, and check whether essential bills would still be covered. If repayment would leave the next week’s budget short, the advance has moved the problem rather than solved it.
My key test is whether the repayment plan works without relying on another loan or advance. I would also decide on a personal borrowing ceiling before opening the app. Making that decision in a calm moment is more useful than trying to set a limit while focused on an urgent expense.
What the WeDollar experience is really good at
The strongest part of the app is its narrow focus. Instead of trying to become a full personal-finance dashboard, WeDollar puts the cash-advance idea at the center. That makes it easier for a user who has one immediate problem—such as a necessary purchase before payday—to understand why the app exists. I appreciate that kind of directness because financial apps can become confusing when budgeting, investing, credit monitoring, and borrowing are all mixed together.
In practical use, I would begin by treating the app as a screening and decision tool, not as an automatic solution. I would open it when I knew the amount needed, check the available borrowing information carefully, and compare the total repayment obligation with the cost of another option. That workflow is more useful than simply tapping through the first offer that appears. The important question is not only how quickly money may arrive, but how comfortably the repayment fits the next budget.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A realistic example would be a household facing a necessary replacement item shortly before regular income arrives. WeDollar may be worth checking when waiting is genuinely impractical and the user already knows where repayment will come from. I would write down the amount required first, then compare it with the amount offered, any visible charges, and the repayment timing shown in the app. If the advance solves a short gap without creating another one, the convenience has a clear purpose.
That same situation also shows why the app should not be used casually. An instant advance can feel smaller than it really is because the borrowing decision happens on a phone, often during a stressful moment. I would avoid entering an amount simply because it is available. Borrowing only what addresses the immediate expense is a useful discipline, especially when the app makes the process feel quick.
A focused tool rather than a complete money manager
WeDollar belongs in the finance category, but I would not use it as a replacement for a bank account, a spending tracker, or a long-term budgeting system. Its value is concentrated around access to a cash advance. That distinction matters for expectations: someone looking for bill reminders, detailed spending categories, savings goals, or investment tools should choose a different type of app.
Compared with asking a traditional bank about a personal loan, the mobile approach can feel less cumbersome for a small, urgent need. A bank may be the better route for a larger planned expense, a longer repayment period, or a borrower who wants an established relationship and broader account services. Compared with borrowing from friends or family, WeDollar offers a more formal path, but it also means the user must judge the financial cost and repayment obligation rather than relying on personal flexibility.
Compared with a credit card, an advance may be easier to consider when the user does not want to use an existing card balance. However, “instant” should never be interpreted as “free” or automatically cheaper. The right comparison is the complete amount repaid, the timing of each payment, and the consequences of missing that schedule. I would make that comparison before accepting anything, even if the need feels urgent.
Small habits that make the app safer to use
My first practical tip is to prepare a repayment snapshot before opening the app. I would note the next expected income, essential bills, and the maximum amount that could be repaid without cutting into necessities. This takes only a few minutes, but it changes the experience from impulse borrowing into a controlled decision. If the repayment would depend on another advance, I would stop there rather than continue.
My second tip is to read the final review screen slowly. In a fast cash-advance flow, the most important information may be less visually exciting than the approval message. I would look for the amount received, the total amount due, the timing of repayment, and any conditions attached to the offer. I would also save a personal note of those details so I could check them later without relying on memory.
A third useful habit is to separate eligibility from affordability. Being shown an advance does not mean it is a good fit for the household budget. I would ask two different questions: “Can I receive this?” and “Can I repay this comfortably?” The second question is the one that should decide whether to continue.
There is also a privacy and device-safety angle to consider. Because this is a finance app, I would install it only from the official app marketplace, keep the phone protected with a screen lock, and avoid reviewing sensitive borrowing information on a shared device. I would not send screenshots of an offer through casual messaging channels. These steps are not glamorous, but they are sensible whenever personal financial information is involved.
Where the experience needs caution
The main weakness is not that the concept is unclear; it is that speed can encourage a rushed decision. A short path from need to application is useful, but it can also reduce the pause that normally helps people compare alternatives. I found that the app makes the user’s own discipline especially important. It should be approached with a written limit and a clear repayment plan, not opened merely to see how much might be available.
I would also be careful about treating the app as a dependable emergency fund. A borrowing service can help with a temporary gap, but it does not remove the underlying reason the gap occurred. If unexpected expenses happen repeatedly, a budget review, a conversation with the bill provider, or a longer-term savings plan may be more helpful. WeDollar is better suited to an isolated shortfall than to covering ordinary living costs month after month.
Another point of friction is the need to compare the offer with alternatives yourself. The app’s purpose may be straightforward, but the best financial choice depends on personal circumstances. A user who already has access to a lower-cost option may gain little by choosing an advance simply because it appears faster. I would compare the full repayment obligation rather than focusing on the amount deposited or the speed of the process.
Anyone who is uncomfortable with digital borrowing should not feel pressured to use it. A bank branch, a credit union, a trusted financial counselor, or a direct conversation with a service provider may be preferable when the situation is complex. Likewise, users who need a large loan, extended repayment, or detailed financial planning should probably look elsewhere. The app’s focused design becomes a limitation when the financial problem is broader than a short-term cash gap.
Questions I would settle before relying on an advance
A common practical question is whether an advance is guaranteed simply because the app is available to install. I would not plan a payment around that assumption. I would treat the app as a place to review a possible option and make no commitment to an expense until I had checked what was actually presented and whether it suited my budget.
I would also ask whether the amount offered is the amount I should take. Those are different decisions. If the available amount is greater than the expense, I would stick to the smaller amount needed—or decline if the repayment terms do not work. A larger offer does not make an expense more urgent, and accepting extra borrowing can make the next budget harder to manage.
Another question is what to do when the repayment date conflicts with another essential bill. I would not assume that the schedule can be changed or that a later payment will be harmless. I would review the terms shown before accepting and, if the timing leaves necessities uncovered, compare another route or contact the relevant bill provider. A possible advance is not a good fit just because it addresses today’s problem.
Finally, I would decide in advance what would make me stop. Unclear repayment details, an amount that exceeds the need, or a budget that only balances if everything goes perfectly are all reasons to pause. The useful habit here is to set those boundaries before the application feels urgent, so the decision does not depend on optimism in the moment.
Who will get the most from it
I think WeDollar is most suitable for an adult who understands the difference between a temporary advance and income, has a specific short-term need, and can identify a realistic repayment source. The Everyone content rating makes the app broadly accessible from a store perspective, but responsible borrowing still requires adult financial judgment. I would recommend it to someone who wants a quick mobile starting point and is willing to inspect every condition before proceeding.
It may also suit users who dislike navigating a large banking app for a single borrowing inquiry. The dedicated purpose makes the initial decision easier to frame. You are not opening it to reorganize an entire financial life; you are checking whether a cash advance is appropriate for one situation. That clarity is the app’s biggest practical strength.
I would recommend skipping it if the intended borrowing is for entertainment, repeated discretionary purchases, or expenses with no clear repayment plan. I would also skip it when the user is already juggling several debts or expects to borrow again to meet the next payment. In those cases, the apparent convenience could make a difficult situation harder to see clearly.
The app was released on October 14, 2025, and the current version is 2.0.2. It supports devices running Android 7.0 or later, which makes it usable on many older Android phones. That broad compatibility is helpful for people who do not own a recent device, although I would still keep the operating system and security updates current when handling financial information.
My final recommendation
WeDollar is a useful, narrowly defined finance app when the user needs to investigate an instant cash advance and is prepared to make a careful repayment decision. I like its direct purpose, free availability, and approachable mobile format. The developer, Voronkov Moner App, has built something that can be relevant in a genuinely time-sensitive situation without pretending to be a complete financial-management system.
My recommendation comes with a firm condition: use it as a comparison point, not as permission to borrow. Check the total obligation, write down the repayment timing, and compare the offer with a bank, card, family arrangement, or negotiated bill payment when those alternatives are available. If the numbers fit a short and clearly defined gap, the app may be worth trying. If the numbers only work by borrowing again, it is the wrong tool.
In short, I would recommend Borrow Cash Instantly WeDollar to a careful user facing a one-off cash shortage, while advising anyone with ongoing debt pressure or a larger financial need to choose a more comprehensive option. Its convenience is real, but its best feature is the focused access it provides—not a reason to stop thinking before borrowing.
Frequently Asked Questions
01What is Borrow Cash Instantly WeDollar?
Borrow Cash Instantly WeDollar appears to be a financial app designed to help eligible users request short-term cash advances or loans through a mobile device. After creating an account and providing the requested personal and financial information, users may be shown available borrowing options, repayment terms, fees, and eligibility requirements. Availability can vary by location, credit profile, and the lending partners connected with the service.
02How does the borrowing process work in WeDollar?
Typically, the process begins with registration, identity verification, and completion of an application that may include income, employment, banking, or other financial details. If approved, the app should display the amount offered, repayment schedule, applicable interest, and additional charges before acceptance. Read this information carefully and confirm the total repayment cost rather than focusing only on the advertised borrowing amount.
03Are there fees or interest charges when using Borrow Cash Instantly WeDollar?
Borrowing through a cash advance or loan application may involve interest, origination fees, service charges, late-payment penalties, or other costs. The exact amount depends on the offer, your location, and the lender’s terms. Before accepting any agreement, review the annual percentage rate, total amount due, payment dates, automatic-debit conditions, and cancellation rules so there are no unexpected expenses.
04Is Borrow Cash Instantly WeDollar safe and legitimate to use?
Before submitting sensitive information, users should verify the app’s developer, privacy policy, customer-support details, permissions, and lender disclosures on the official app store listing. A trustworthy service should clearly explain how personal and banking data are collected, stored, shared, and protected. Avoid applications that request unnecessary permissions, promise guaranteed approval, or demand upfront payments before explaining the loan terms.
05What should I do if I cannot repay a WeDollar loan on time?
If repayment may be difficult, contact the provider or lender as soon as possible instead of ignoring payment reminders. Ask whether an extension, revised payment arrangement, or hardship option is available, and confirm any additional fees in writing. Late or missed payments can result in penalties, repeated debit attempts, collection activity, or possible credit-reporting consequences, depending on the agreement and local regulations.


